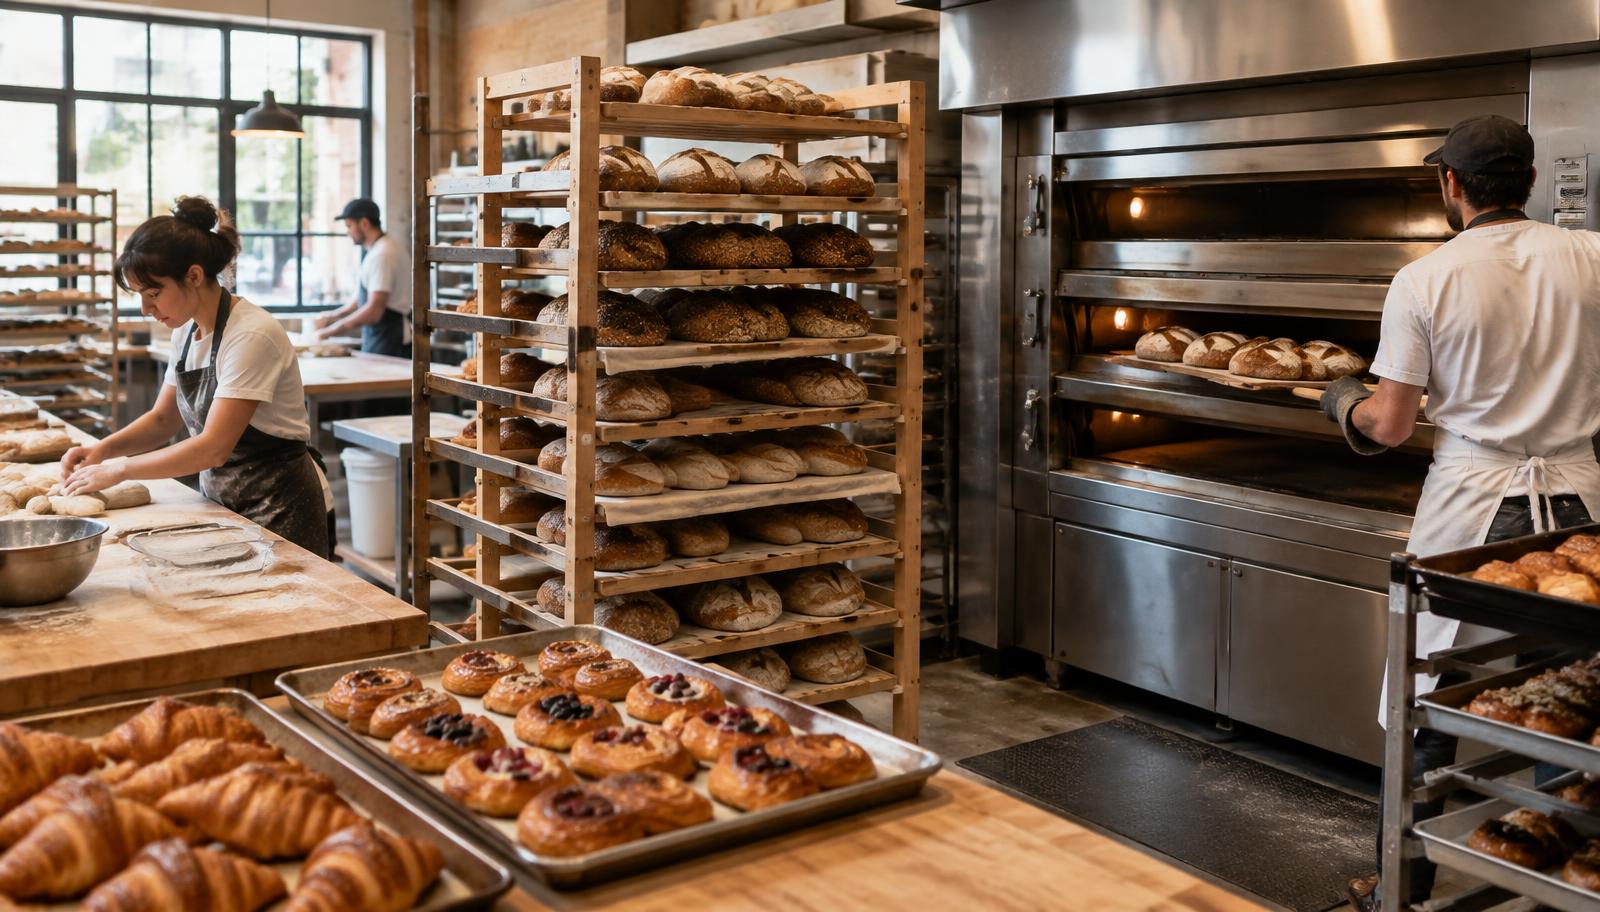
Richmond bakery insurance is mostly about production risk. Many of the bakeries we see here are wholesale or commissary-based rather than retail-first, which puts equipment, refrigeration, delivery vehicles and contract requirements ahead of the counter exposure.
We write these programs from Antioch as an independent brokerage, and we start by separating what the building owner insures from what you do.
What bakery insurance should include
Bakeries sit between retail and light manufacturing, and the insurance should reflect both. You need general liability for the front of house, property at replacement cost for ovens, proofers, mixers and refrigeration, and product liability that responds if an allergen makes it into the wrong box — the claim most likely to become expensive.
If you sell wholesale to grocers, restaurants or coffee shops, check the certificate requirements in those contracts before renewal. Additional insured status and waivers of subrogation are routinely demanded and just as routinely missing.
Ovens, mixers and the cost of downtime
A deck oven or rack oven going down is not just a repair bill; it is days of lost production during the only hours that matter. Equipment breakdown pays for the repair, and business income with a short waiting period pays for the sales you could not make. Ask what the waiting period is — a 72-hour clause on a bakery is close to useless.
Workers' compensation in a hot, early-shift kitchen
Burns, slips on flour dust, and shoulder and wrist strain from repetitive mixing and lifting drive most bakery claims. Crews start before dawn, often short-staffed, which is exactly when injuries happen. Accurate class codes and a documented safety routine are the two levers that move your premium in the direction you want.
Spoilage, contamination and recall
Refrigeration loss ruins dairy, fillings and finished product. Contamination and recall coverage goes further, paying to pull product and notify customers when something goes wrong after it leaves your door. Most bakery package policies include a token spoilage limit and no recall coverage at all.
What we see in Richmond
Power and refrigeration interruptions hit hardest where product sits in volume. If your walk-in holds days of finished goods or fillings, spoilage coverage with a utility-interruption trigger is worth paying for rather than assuming.
Delivery routes across the bridge and around the East Bay also mean vehicles and drivers. MVR checks and a proper commercial auto policy are cheaper than the first at-fault accident in a van full of product.
Questions Richmond owners ask us
Does spoilage coverage pay for a power outage?
Some forms do and some require a mechanical breakdown on your own equipment. The trigger language is the whole question, and we read it before placing coverage.
What insurance do grocery accounts require?
Typically $1–2 million general liability including products, additional insured status, and proof of workers' compensation. Some also ask for auto liability if you deliver.
Are my delivery drivers covered?
Under a commercial auto policy, yes, if the vehicles and drivers are listed. Personal vehicles used for work need hired and non-owned coverage added to the business policy.
Get a bakery quote for your Richmond business
Tell us your equipment list, annual sales and payroll and we'll benchmark your current coverage against what local bakeries are actually paying. We are an independent brokerage based in Antioch, serving Contra Costa County and the wider Bay Area. CA License #0D90958.
Other cities we write this coverage in
See our full Bakery & Commercial Baking Insurance overview.