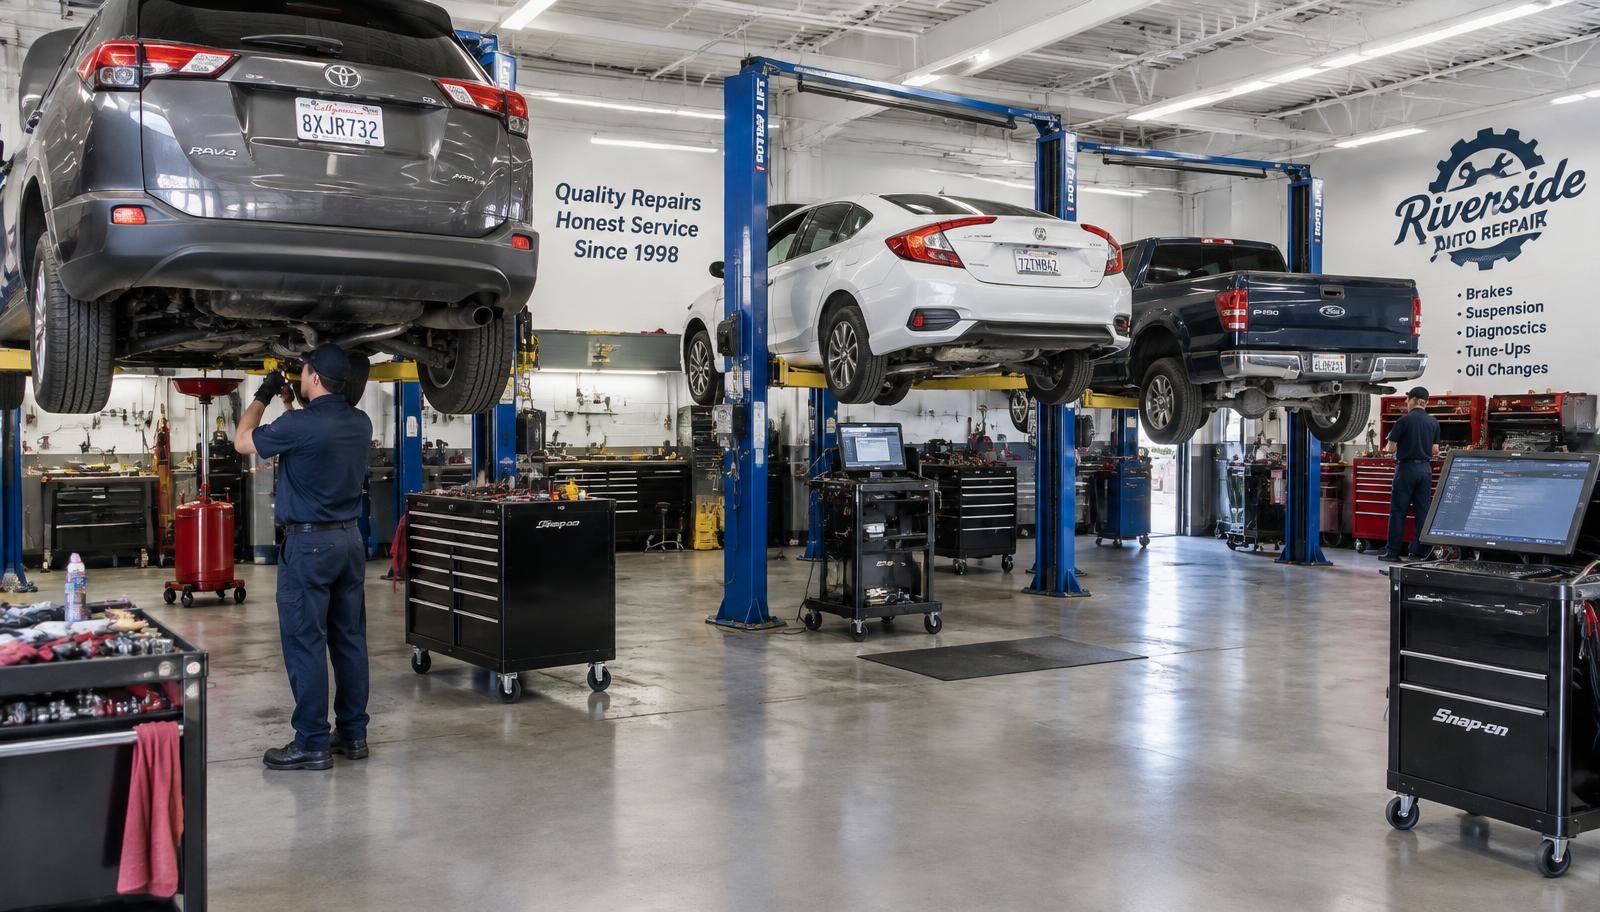
Walnut Creek auto repair shop insurance turns on vehicle values. European and luxury service, dealership overflow and specialty work mean the cars in your bays are worth multiples of what a general shop holds, and garagekeepers limits set years ago rarely reflect that.
We review the lot value first, then the diagnostic equipment schedule, then driver controls — in that order, because that is the order the money sits in.
Auto repair shop insurance starts with garagekeepers
Your general liability policy does not cover damage to a customer's vehicle while it is in your care. Garagekeepers legal liability does, and how it is written matters: direct primary pays regardless of fault, legal liability only pays when you are legally responsible. The cheaper form is the one that leaves you explaining to a customer why their car isn't being repaired.
Set the per-location limit against the busiest night of the year, not the average. Cars parked on the lot overnight and vehicles awaiting parts are what get stolen, vandalized or damaged.
Test drives and employee driving
Test drives are the most common serious loss a shop has, and coverage for them sits at the intersection of garage liability and auto. Keep a written key-control and test-drive policy, pull MVRs on anyone who drives, and make sure your policy covers the drive — not just the repair.
Lifts, compressors and diagnostic equipment
A failed lift is both a safety event and a revenue event. Equipment breakdown covers the hardware; business income covers the bays you can't use. Scan tools and alignment racks are often under-scheduled on property policies because their replacement cost has risen faster than most owners have updated their values.
Workers' comp and hazardous materials
Technician claims trend toward back, shoulder and hand injuries, plus solvent exposure. On the environmental side, used oil, coolant, solvents and parts washers put you under county hazardous-waste rules; a pollution endorsement or standalone environmental policy fills a gap standard garage policies exclude outright.
What we see in Walnut Creek
A dozen luxury vehicles on a lot can exceed a standard garagekeepers limit on its own. If you routinely hold high-value cars, the limit and the deductible both need to be deliberate choices rather than package defaults.
Advanced diagnostic and calibration equipment has also become a major property item. ADAS calibration rigs and scan tools cost more to replace than most policies have scheduled, and downtime without them stops the work entirely.
Questions Walnut Creek owners ask us
How do I insure high-value customer vehicles?
By setting the garagekeepers limit to your peak lot value and, where appropriate, adding a higher limit for specific vehicles. We would rather document that in advance than argue value after a loss.
Is my calibration and diagnostic equipment covered?
Only to the extent it is scheduled at replacement cost. We update those values at every renewal because this equipment has climbed in price faster than most shops realize.
Does insurance cover lost income if a lift goes down?
Equipment breakdown covers the repair, and business income covers the bays you cannot use during the outage, provided the waiting period is short enough to matter.
Get a repair shop quote for your Walnut Creek business
Send your current declarations and a rough count of vehicles on the lot overnight and we'll check your garagekeepers limit first. We are an independent brokerage based in Antioch, serving Contra Costa County and the wider Bay Area. CA License #0D90958.
Other cities we write this coverage in
See our full Commercial Auto Insurance overview.